Free eventsMedicare · Social Security · Retirement taxes · Roth conversions · Estate planningSee dates & register →
Services

Planning. Strategy. Results.

We take a holistic approach, guiding you from your annual tax return through how you draw income in retirement with the aim of reducing the taxes you pay.

Video: how Planning, Strategy and Results fit together (under a minute)
01 · PLANNING

It starts with your tax return.

We review your return line by line to look for missed deductions, credits and planning opportunities.

The goal
  • Manage tax liability
  • Plan for risk
  • Manage cash flow

Reducing taxable income

Contribute to workplace or retirement plans and consider the adjustments and age-based benefits you may qualify for:

  • 401(k) and traditional IRA contributions
  • Extra standard deduction at age 65+
  • Qualified charitable distributions (70½+)
  • Health savings and self-employment adjustments
Deductions

Standard deduction or itemize? We compare both methods every year. The three largest itemized deductions are:

  1. Mortgage interest
  2. State and local property taxes
  3. Charitable gifts

Tip: track medical, property tax and charitable receipts throughout the year, not just in April.

Tax credits & second opinion

Credits reduce your tax bill dollar for dollar. We also review prior returns for overlooked credits and carryovers:

  • Retirement savings contributions credit
  • Family, dependent and education credits
  • Capital-loss and charitable carryovers
  • Prior-year filing errors and missed refunds
Free PDF · Retirement Tax Planning

RMD planner

Track required minimum distributions and plan withdrawals.

By submitting, you agree to receive the requested PDF at the email provided. View our Privacy Policy.

02 · STRATEGY

Four principles we plan by.

Good retirement tax strategy coordinates your investments, your tax brackets and your withdrawal timeline before required distributions force your hand.

On risk

Manage risk
Protecting what you have built matters as much as growing it, so we weigh downside risk alongside potential return.
Weigh risk against reward
We look for opportunities where the potential reward appears to justify the risk.

On taxes

Plan for after-tax results
We look at what you may keep after taxes, not only what you earn.
Diversify tax treatment
Spread savings across taxable, tax-deferred and tax-free accounts, which may help keep large required withdrawals from pushing your income into a higher bracket.

All investing involves risk, including loss of principal. No strategy can eliminate risk.

How retirement income is taxed

Taxes in Retirement guide →
Income sourceBucketHow it’s generally taxed
PensionsTax-deferredTaxed as ordinary income
Social SecurityPartly taxableUp to 85% may be taxable, depending on your other income
401(k) / 403(b)Tax-deferredPre-tax contributions; withdrawals taxed as ordinary income
Traditional IRATax-deferredWithdrawals taxed as ordinary income; required minimum distributions apply
Roth IRATax-freeFunded after tax; qualified withdrawals are tax-free
Non-retirement savingsTaxableInterest taxed as ordinary income; qualified dividends and long-term gains at capital-gains rates
03 · RESULTS

In retirement, we plan withdrawals across all three buckets with your tax bill in mind.

The typical withdrawal order
  1. FIRSTTaxableBrokerage and savings accounts
  2. NEXTTax-deferredTraditional IRAs, 401(k)s, 403(b)s
  3. LASTTax-freeRoth accounts, usually saved for last
When we break the rule
Start withdrawals early

With large traditional IRA or 401(k) balances, beginning planned withdrawals before age 73 spreads the income across more years and may help limit a sudden jump in tax brackets and Medicare premiums.

Explore withdrawal strategies →
Convert to Roth in low-bracket years

In lower-income years between retiring and starting required minimum distributions, converting part of a traditional IRA to a Roth uses today’s known tax rates and may create tax-free growth later. Tax laws can change.

Roth Conversions guide →

Keeping a mix of account types may give you the flexibility to manage your tax bill every year of retirement.

Explore Turning 65 →
Common questions

Tax Planning & Services FAQ

What is the difference between tax preparation and tax planning?

Tax preparation records what already happened last year and files an accurate return. Tax planning looks ahead across multiple years so your IRA withdrawals, Roth conversions, Social Security claiming and Medicare premiums work together, which may lower what you owe over your retirement.

Can you review a tax return that was prepared somewhere else?

Yes. Every new client can bring their prior return for a complimentary second opinion. Mary Garza reviews it line by line for missed deductions, credits or reporting errors at no cost and with no obligation.

When is the best time to start retirement tax planning?

The years just before and after you retire, especially between ages 60 and 73, can offer a wider window to manage tax brackets, plan for the 2-year Medicare lookback and consider Roth conversions before required minimum distributions begin.

What should I bring to a first consultation?

Bring your most recent tax return, any retirement account or Social Security statements, and your questions. We’ll review where you stand and outline clear next steps in plain English.

This page is general education, not tax, legal or investment advice. Investing involves risk, including loss of principal. Tax rules change and your results will vary.

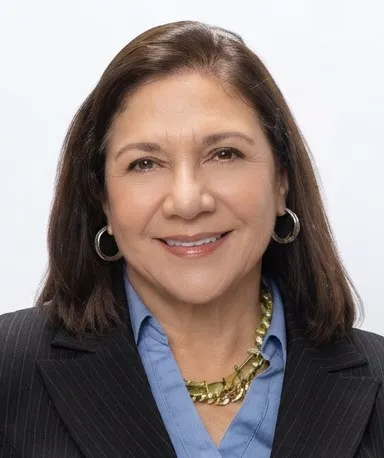
Mary Garza, tax and retirement planning advisor
Next step

Start with a conversation.

A 30-minute consultation with Mary to review your return, answer your questions and map out what’s next.

More resourcesFree checklists, guides, tools and webinars
Visit the resource center